Back to Bizweek
SEARCH AND PRESS ENTER
Latest News
Tourism and reserves strengthen as inflation and trade pressures persist

Stronger tourism receipts and a further accumulation of foreign exchange reserves are providing support to the economy, but rising headline inflation, a widening merchandise trade deficit and subdued industrial expansion are creating a less even picture. CareEdge Africa’s September 2026 economic update, released on 16 September, describes an economy receiving support from services and external buffers while remaining exposed to fuel prices, imported inflation and weak export growth.

A rebound in visitors and robust tourism spending are providing much of the momentum in the latest economic data, even as the higher cost of fuel pushes inflation close to 5 per cent and the merchandise deficit continues to widen. CareEdge Africa characterises the picture as one of “mixed signals”, with stronger reserves giving policymakers room to absorb external pressure but structural trade imbalances continuing to weigh on the rupee.

The September update comes as the Bank of Mauritius keeps its policy rate at 4.75 per cent and the economy navigates higher commodity costs, geopolitical disruption and uneven performance across its productive sectors.

Industrial production expanded by 1.7 per cent year-on-year during the first quarter of 2026, a positive but comparatively modest rate. Manufacturing, which accounts for 84.8 per cent of industrial output, grew by 1 per cent. Non-export-oriented enterprises expanded by 2.1 per cent and sugar milling increased by 3.9 per cent, while export-oriented enterprises contracted by 6.4 per cent.

Electricity, gas, steam and air-conditioning supply recorded the strongest sectoral increase, rising by 8.8 per cent from a year earlier. Water supply, sewerage, waste-management and remediation activities grew by 2.3 per cent, while mining and quarrying declined by 2.3 per cent.

The quarterly comparison was considerably weaker: total industrial production fell by 18.2 per cent from the final quarter of 2025, which CareEdge attributed largely to the seasonal pattern of industrial and manufacturing activity.

The agency expects production to remain moderately positive, supported by manufacturing and growing demand for electricity and utility services. It nevertheless sees weak mining output and pressure on export industries, particularly textiles, as constraints on faster growth.

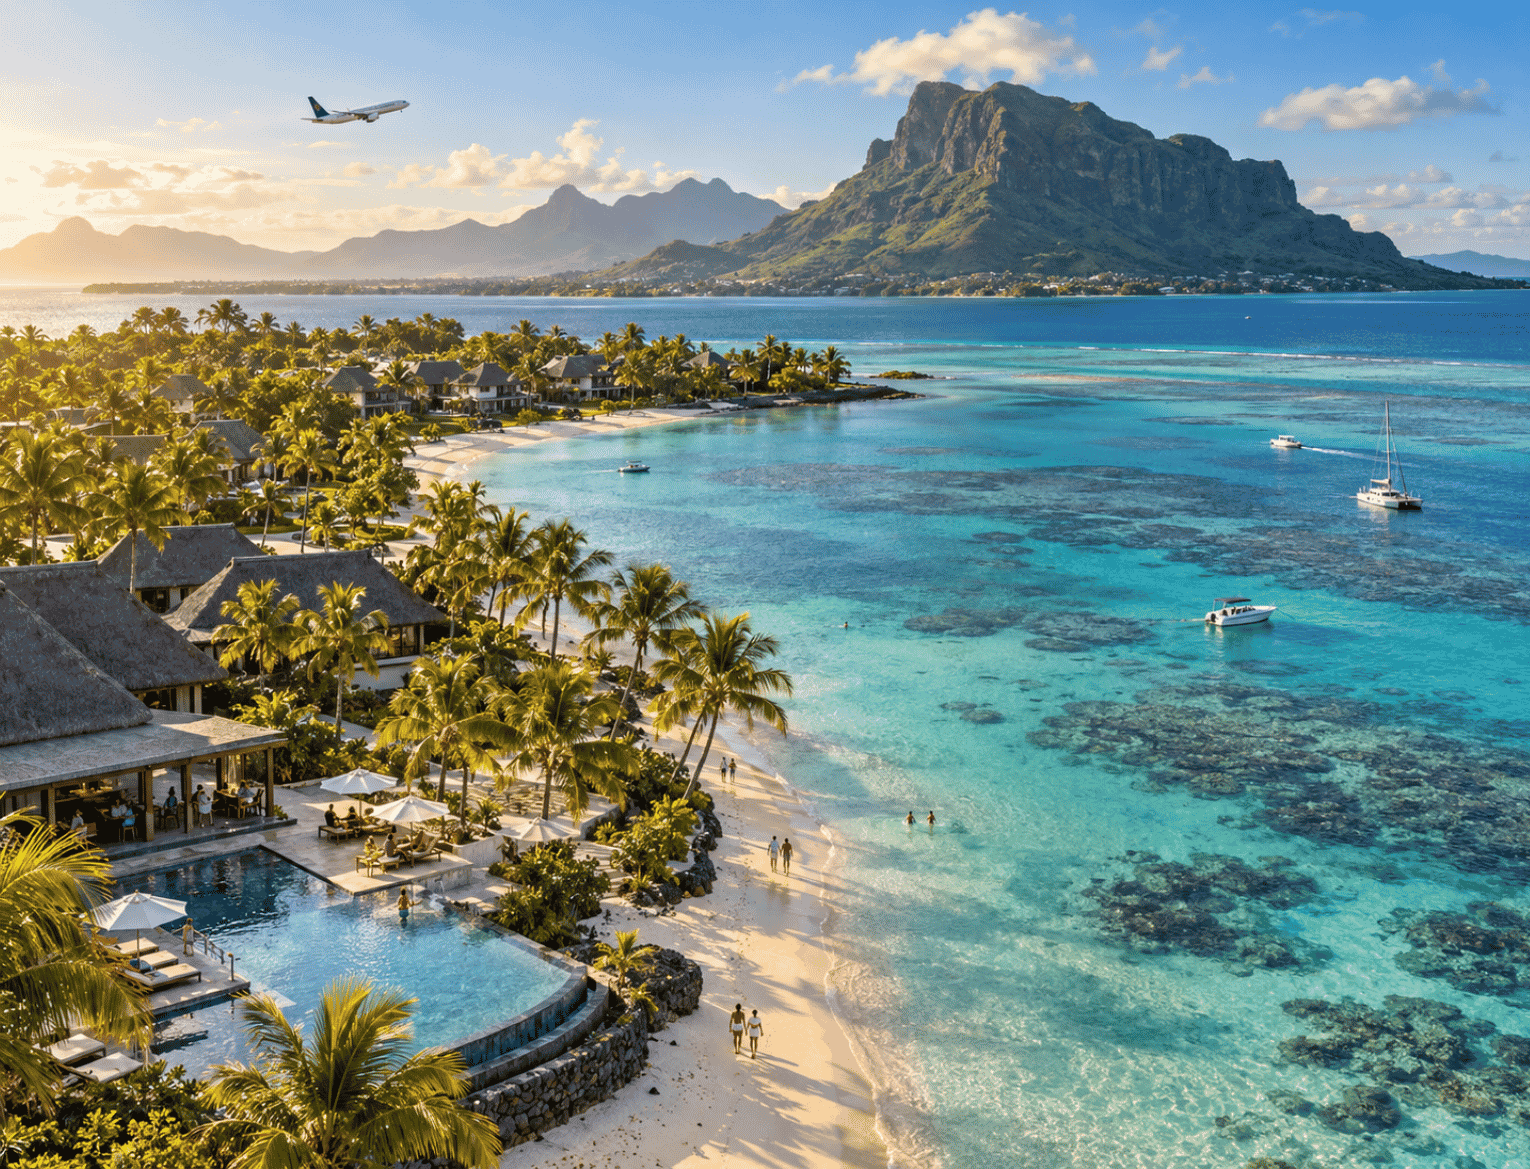
Tourism is offering a stronger counterweight. Visitor arrivals rose by 6.6 per cent year-on-year in August to 123,102, lifting arrivals for the first eight months of 2026 to 927,735, an increase of 2.7 per cent from the corresponding period last year.

Europe remained by far the largest source region, accounting for 62.1 per cent of visitors in August and recording year-on-year growth of 7.6 per cent. France remained the principal European market, followed by the UK and Germany.

The faster growth, however, came from Asia. Arrivals from the region increased by 29.3 per cent year-on-year, supported by a 12.1 per cent rise from India, a 65.2 per cent increase from the Middle East and 9 per cent growth from China. India accounted for more than half of arrivals from the Asian region.

Tourism earnings have grown significantly faster than visitor numbers, pointing to continued resilience in expenditure per traveller. Gross tourism earnings reached MUR9.1bn in July, 16 per cent higher than a year earlier. During January to July, receipts totalled MUR65bn, an increase of 17.6 per cent year-on-year. CareEdge said diversification towards Asia, the Middle East and Africa, alongside improved air connectivity and new routes, should help support activity during the remainder of the year.

The inflation picture is less comfortable. Headline inflation accelerated to 4.9 per cent year-on-year in August from 4.4 per cent in July. Transport prices recorded the largest monthly increase, at 1.39 per cent, followed by food and non-alcoholic beverages at 1.24 per cent.

A key factor was the increase in the retail price of fuel by the State Trading Corporation, with petrol rising from Rs64.25 to Rs70.25 per litre. Higher fuel costs have implications beyond motorists, feeding into transport, distribution and broader operating expenses.

Yet the underlying inflation picture moved in the opposite direction. Core inflation declined to 4 per cent in August from 4.3 per cent in July. This was the second consecutive month in which core inflation remained below headline inflation, suggesting that the recent acceleration was concentrated largely in volatile categories such as fuel and food rather than being broadly distributed across the consumer basket.

Headline inflation is nevertheless above the midpoint of the Bank of Mauritius’ 2-5 per cent target band and is close to the central bank’s projected average of 5 per cent for 2026. CareEdge sees risks tilted towards further price pressure. Higher international energy and commodity prices, disruption to shipping routes, exchange-rate weakness and geopolitical tensions could all raise imported costs in an economy heavily reliant on foreign goods.

Food subsidies, softer domestic demand and the effects of tighter monetary policy should partly offset those pressures, but the agency expects headline inflation to remain close to the upper end of the central bank’s target range during the remainder of 2026.

External trade presents another vulnerability. The merchandise trade deficit widened to MUR23.8bn in June from MUR18.9bn a year earlier as imports increased by 18.8 per cent while exports grew by only 5.6 per cent. The import bill was pushed higher by a 34.4 per cent increase in mineral fuels, lubricants and related products, a 30.5 per cent increase in chemicals and related products, and growth of 22.3 per cent in manufactured goods classified chiefly by material. Food and live-animal imports rose by 8.2 per cent.

Exports received support from chemicals and related products, which increased by 51.5 per cent, as well as manufactured goods and ships’ stores and bunkers. Those gains were partly offset by a 12.1 per cent contraction in machinery and transport-equipment exports, a 6.6 per cent fall in miscellaneous manufactured articles and a 2.9 per cent decline in food and live animals.

The deterioration is also visible over the first half of the year. The cumulative merchandise deficit reached MUR114.3bn between January and June, compared with MUR100.8bn in the same period of 2025.

Imports increased by 8.8 per cent while exports grew by just 0.3 per cent. CareEdge said continued geopolitical tensions and disruption to important shipping routes could raise freight, energy and import costs further. It nevertheless pointed to the extension of preferential access to the US market under the African Growth and Opportunity Act through 2028 as a source of greater certainty for Mauritian exporters, particularly the apparel industry.

Tourism and other services exports should continue supporting the balance of payments, but the report cautioned that faster merchandise-export growth will ultimately be required to reduce pressure on the trade account.

For now, the country’s reserve position provides a significant buffer. Gross official international reserves rose to MUR485.9bn, or US$10.2bn, in August from MUR460.9bn, or US$9.7bn, in July.

On the conventional measure excluding Global Business Company services, this increased import cover to 14.4 months from 13.7 months. Under the Bank of Mauritius’ broader measure incorporating GBC-related imports, cover rose to 10.5 months from 10 months. The currency nevertheless continues to reflect the underlying imbalance between import demand and foreign-exchange earnings.

The rupee averaged MUR47.6 to the US dollar and MUR55.2 to the euro during August. Against the dollar, it appreciated by 1.4 per cent over the three months to August, but remained 3.1 per cent weaker than a year earlier. Between March and August, it recorded a cumulative depreciation of 1.1 per cent.

Against the euro, the rupee appreciated by 0.8 per cent over the three months to August but was 2.2 per cent weaker year-on-year. CareEdge linked the continuing depreciation pressure to the structural merchandise deficit, sustained demand for foreign currency to pay for imports and broader dollar strength.

The Bank of Mauritius has continued to intervene in the foreign-exchange market, injecting a cumulative US$80mn between January and September. This was below the US$115mn injected during the corresponding period in 2025. CareEdge said the reduction could point to some improvement in foreign-exchange liquidity, although underlying demand for hard currency remains high.

Skip to content