Back to Bizweek
SEARCH AND PRESS ENTER
Latest News
Why investors should spend less time predicting markets and more time understanding what drives returns

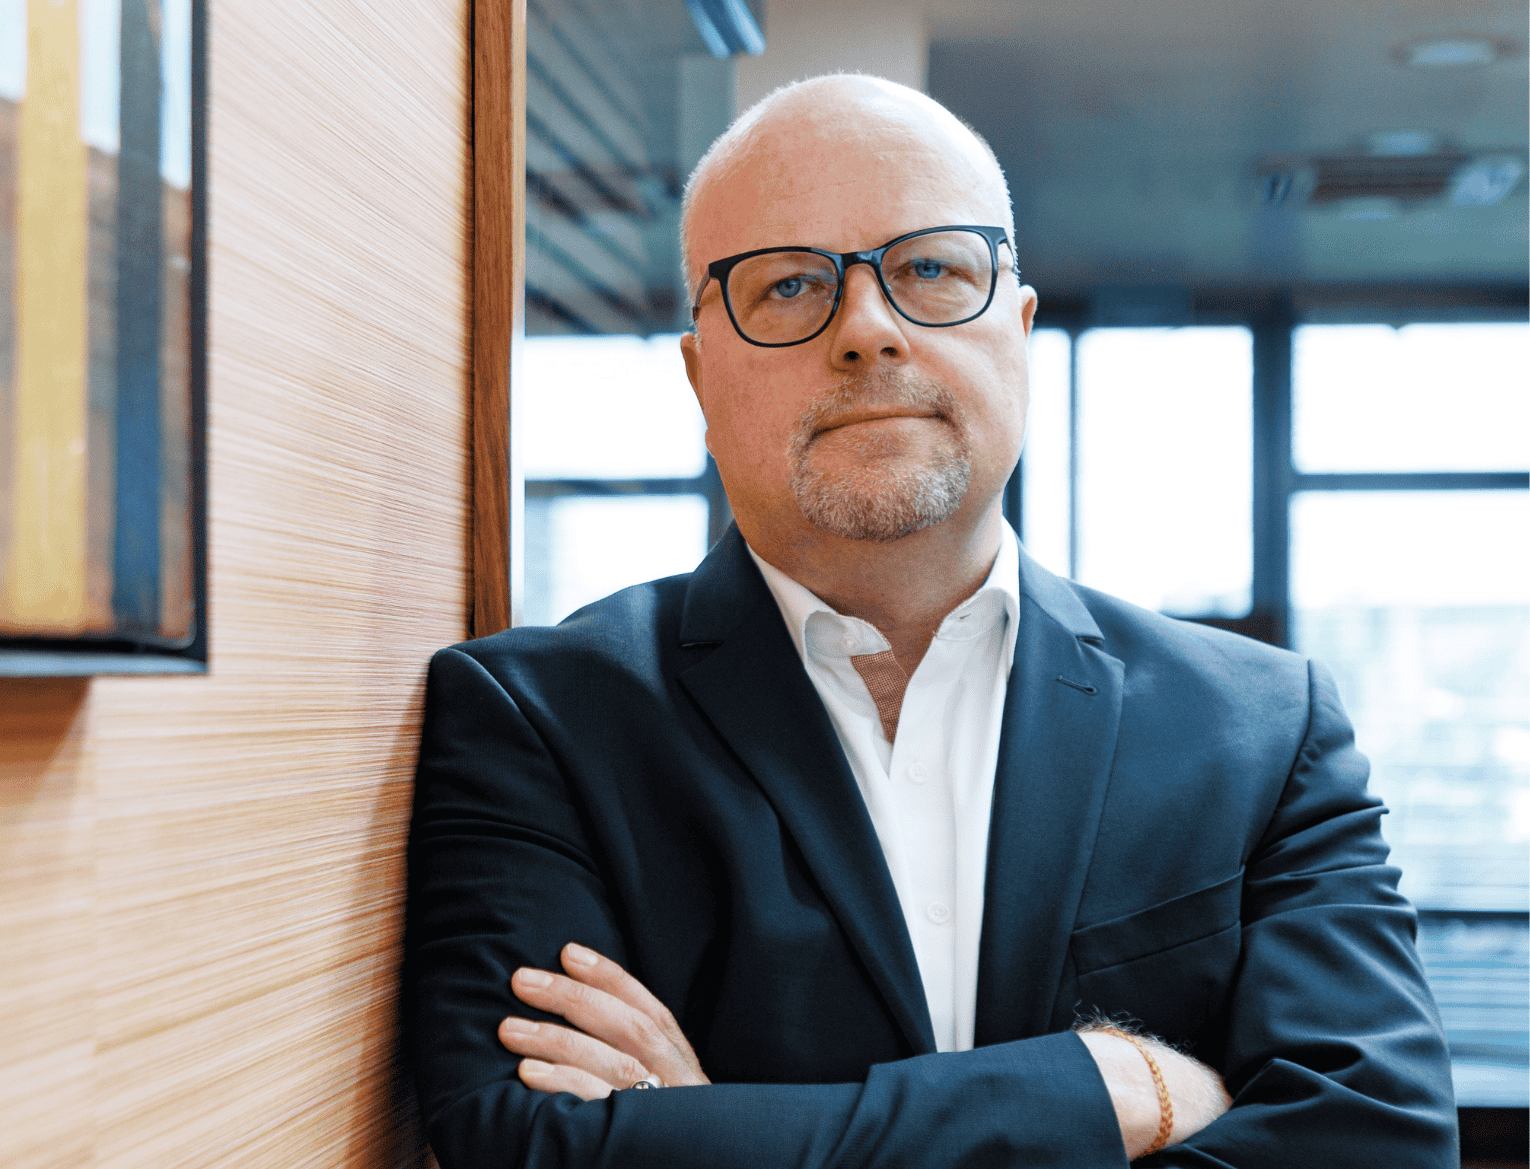
Oliver Müller, Chief Investment Officer, Accresco Investment Management

The Anatomy of an Equity Return

Every equity return tells more than one story. Part comes from simply owning the market; part from systematic exposures to certain factors such as Growth, Value, Quality or Momentum; part from the investment style built around them; and only the residual may deserve to be called alpha, the value added by active investment decisions beyond those underlying exposures. That distinction matters because investors can easily mistake a favourable cycle for skill, pay active fees for systematic exposure, or abandon a capable manager when it is the style rather than the stock-picking that is temporarily out of favour. Understanding those layers is therefore a better starting point than trying to forecast where markets are headed next.

By Oliver Müller, Chief Investment Officer, Accresco Investment Management

After more than three decades in financial markets, I have become less interested in predicting the next twelve months and more interested in understanding what has driven returns over the last cycle. Forecasts are not irrelevant: interest rates, economic growth, politics, currencies and technological change all matter, often profoundly. But recognising that they matter is very different from forecasting their direction, timing and market impact with enough consistency to anchor an investment process. Even a correct macroeconomic view can lead to a poor investment if the market has already discounted it. In my experience, attribution is therefore often more useful than prediction, because returns leave evidence behind and that evidence can tell us far more about what actually worked than another forecast about what might happen next.

Where a return comes from

When investors discuss equity performance, they often treat the return as if it came from a single source. In practice, it is more useful to think of it as a series of layers. At the foundation sits beta, the return available from owning the equity market itself. Investors can then tilt that market exposure towards systematic characteristics, or factors, such as Growth, Value, Quality or Momentum. Those factors can in turn be combined with additional investment rules and disciplines to form broader styles. 

Only after accounting for those layers does it make sense to talk seriously about alpha. In its most useful sense, alpha is not simply the amount by which a portfolio beats a broad index. It is the return that remains after the market, factor and style exposures embedded in the portfolio have been accounted for, and which may therefore be attributable to active decisions such as security selection, valuation judgement, position sizing and portfolio construction. The boundaries are inevitably imperfect, because styles are themselves partly built from factor exposures and active managers carry systematic exposures whether they intend to or not. The value of the hierarchy lies in making those distinctions explicit: which part of the return came from the market, which from systematic factor and style exposures, and which, if any, can reasonably be attributed to active judgement.

The market provides the foundation

Before searching for factors, styles or alpha, it is worth recognising how much of long-term wealth creation has historically come from simply owning equities. From 1928 through 2025, US equities generated an annualised return of approximately 10%, compared with 5.6% for gold, 4.5% for bonds, 4.2% for property and 3.4% for Treasury bills. Those annual differences become extraordinary through compounding: $100 invested in US equities at the beginning of 1928 would have grown to roughly $1.2 million by the end of 2025, compared with about $21,000 in gold, $7,700 in bonds, $5,600 in property and $2,600 in Treasury bills.

The explanation is not simply that equities are riskier, and investors have therefore demanded a higher return. It also reflects the economic nature of the asset itself. A share is a claim on a productive enterprise, and productive enterprises can create value internally by reinvesting earnings, improving productivity, developing new products, raising prices or entering new markets. When capital can repeatedly be reinvested at attractive rates, future earnings are generated on an expanding economic base. 

None of this means that equity ownership offers a smooth ride. Recessions, valuation contractions, financial crises and prolonged bear markets are part of the historical record, and the ~10% annualised return was earned precisely by investors who had to live through them. 

That long-term equity return is the starting point for everything that follows. In portfolio terms, it is beta: the return available from broad participation in the market before any factor tilt, style choice or active decision is introduced. The investment challenge is therefore not to replace that return, but to ask whether those additional layers can improve its characteristics and, over time, add to it.

What Quality adds

Once the market return is established as the foundation, the next question is whether systematic characteristics can improve the odds. Factor investing attempts to do precisely that, although factor research is particularly vulnerable to data mining: given enough variables, securities and historical periods, it is not difficult to discover something that once appeared to work. The more persuasive factors are therefore those for which the empirical record is supported by an economic rationale for why the effect might persist.

Quality is one of them. Companies with persistently high profitability, stable earnings and prudent balance sheets possess advantages that are economically intuitive rather than merely statistical. They can finance a greater proportion of growth internally, absorb shocks more comfortably and continue investing when weaker competitors are forced to retrench. In the strongest businesses, these characteristics can become self-reinforcing, as financial strength supports continued investment, investment reinforces competitive advantage and competitive advantage sustains attractive returns on capital.

The empirical evidence is consistent with that logic. In our analysis of global equity factors since the end of 2000, Quality generated approximately 9.2% per annum, compared with 7.4% for the MSCI All Country World Index (“ACWI”). Only Momentum produced a higher return, at 10.4%, but with materially greater volatility of approximately 16.8%. Quality, by contrast, achieved its 9.2% annualised return with volatility of roughly 14.6%, the lowest among the principal factors examined. Its appeal therefore lies not simply in having outperformed the broad market, but in having done so with a comparatively more stable return profile.

The relative stability of Quality becomes even more striking across different market environments. Over rolling 36-month periods, Quality outperformed the ACWI in 82% of all observations in our study. Its hit rate was approximately 80% in rising markets and increased to 92% in falling markets. Momentum showed a markedly different pattern, outperforming in 85% of rising-market periods but in only 30% of falling-market periods.

This suggests that Quality’s historical excess returns have been less dependent on a particular market regime. Momentum is a powerful return phenomenon when price trends persist, whereas Quality rests more directly on the financial strength and economics of the underlying businesses. High profitability, resilient earnings and prudent balance sheets do not determine short-term share prices, but they have historically contributed to a return profile that has proved comparatively robust across both advancing and declining markets.

There is an appealing symmetry here: a factor designed to identify higher-quality companies has also historically produced what might reasonably be described as a higher-quality stream of returns.

From factor to portfolio

The empirical case for Quality does not, by itself, tell an investor how the factor should be owned. Factor labels can create the impression of a single, uniform exposure, when in practice the portfolio that results depends on choices about universe selection, concentration, weighting methodology and rebalancing. Those decisions are not merely technical; they can materially alter the resulting exposure.

Weighting provides a useful example. In a portfolio whose constituent weights remain linked to market capitalisation, a stock that has performed exceptionally well can become progressively more important simply because its share price has risen. Over time, this allows past price performance to exert increasing influence on the portfolio, introducing a Momentum characteristic into what is ostensibly a Quality exposure.

Equal weighting changes that dynamic. Periodic rebalancing reduces positions that have risen furthest and reallocates capital across the other companies that continue to meet the Quality criteria. This is not valuation in the fundamental sense, because no judgement is being made about intrinsic value, but it prevents past share-price appreciation from becoming, in itself, a reason for owning more of a stock.

This was one of the considerations behind the design of Accresco’s Superior Quality 50 (“ASQ 50”) strategy, which equal-weights 50 large-cap companies that meet our Quality and responsible-investment criteria and periodically rebalances the portfolio. ASQ 50 has a historical return series extending to 2012, over which it generated an annualised return of approximately 16.0%, compared with 13.5% for the MSCI ACWI Quality Index. The broader lesson is that factor implementation is itself part of the investment process: two portfolios can begin with the same underlying factor and still produce meaningfully different outcomes depending on how that factor is translated into an investable portfolio.

Even a carefully constructed Quality portfolio, however, leaves one important question unresolved: what price should an investor be willing to pay for a superior business?

When Quality meets valuation

Some of the most expensive mistakes in investing begin with an observation that is entirely correct: this is an exceptional company. A business may possess enviable margins, a formidable competitive position, first-rate management and a long runway for growth, yet none of those characteristics tells us whether its shares are attractive at the prevailing price. If enough future success is already embedded in the valuation, the company can continue to execute extremely well while the shareholder earns a disappointing return.

Investors do not receive the economics of a business in isolation. They receive those economics relative to the expectations already reflected in the price they pay. A superior company can therefore justify a premium valuation, but there is still a point at which the prospective return becomes unattractive, however compelling the underlying business may be.

This is where Quality at a Reasonable Price, or “QARP”, enters the discussion. QARP does not imply that outstanding businesses should trade at average valuations. It simply broadens the investment question: not only whether this is a business we would be comfortable owning for many years, but whether, at today’s price, it still offers an attractive prospective return.

Quality and Value in combination

The intuition is compelling, but a durable investment philosophy needs more than intuition. Robert Novy-Marx’s 2013 paper, The Quality Dimension of Value Investing, provides an interesting piece of evidence. Examining roughly 1,000 large US companies, excluding financials, from July 1963 through December 2012, Novy-Marx combined gross profitability as a measure of Quality with book-to-price as a measure of valuation. Rather than treating Quality and Value as competing approaches, the analysis examined what happened when the two were used together. The resulting “Profitable Value” strategy generated approximately 3.1% per annum of net active return over nearly five decades, with tracking error of 4.7% and an information ratio of 0.66.

What makes the result particularly instructive is not just the long-term return, but what investors had to endure to earn it. The strategy experienced a maximum relative drawdown of 13.4%. Seen retrospectively, that is merely one statistic inside almost half a century of successful results. For the investor experiencing it in real time, however, there was no knowledge of the eventual recovery, only a strategy that appeared to be losing ground while other approaches were working better.

The economics of underperformance

That experience points to a broader feature of systematic investing. Persistent return premia are rarely delivered with enough regularity to make them comfortable to own. If an excess return could be captured with near certainty over every short horizon, capital would migrate towards it, prices would adjust and much of the opportunity would eventually be arbitraged away. The persistence of a premium therefore depends, at least in part, on periods in which investors are either unwilling or unable to remain committed to it.

The challenge is that these periods are far easier to understand in hindsight than while they are unfolding. A strategy can remain economically sound while underperforming for several years, particularly when the market is rewarding a different set of characteristics. The relevant question is therefore not whether underperformance has occurred, but whether the underlying rationale for the strategy remains intact.

When valuation discipline falls out of favour

The recent experience of QARP provides a useful contemporary example. Using the Morningstar Global Wide Moat Focus Index as a systematic proxy for the style, QARP generated approximately 9.7% per annum since 2008, compared with 7.7% for the MSCI ACWI, and outperformed the broad market in 14 of 18 full calendar years. Yet that strong long-term record has included a distinctly less comfortable recent phase: the style underperformed materially in 2023 and 2024, recovered some relative ground in 2025 and has again lagged the broader market year to date in 2026.

The reasons are not difficult to identify. Market leadership has become unusually concentrated in a relatively small number of very large technology and AI-related companies, many of which are outstanding businesses but some of which trade at valuations that make benchmark-sized positions difficult for a valuation-conscious investor to justify. In such an environment, a discipline that explicitly considers price can appear unnecessarily restrictive while the most expensive parts of the market continue to outperform.

Investment styles respond to different characteristics, which are rewarded at different points in the market cycle. The more relevant question is whether the economic rationale for combining strong businesses with valuation discipline has weakened. The long-term evidence, including periods in which the style has previously lagged materially before recovering, gives us little reason to conclude that it has.

The benchmark problem

Once style enters the picture, judging an active manager against the broad market alone can become misleading. Consider a QARP manager who trails the MSCI ACWI by seven percentage points during a period in which QARP itself trails by ten. Relative to the broad market, the manager has underperformed; relative to QARP, the same result represents three percentage points of value added. Neither comparison is wrong, but they answer different questions. The broad index tells us whether the style helped or hurt; the style benchmark tells us whether the manager added value within it.

This matters because alpha is what remains after systematic exposures have been accounted for. A manager who looks exceptional against the broad market may simply have benefited from persistent tilts towards Growth, Momentum or Quality; conversely, a capable manager can look weak when the underlying style itself is temporarily out of favour. Distinguishing style from skill is therefore essential to judging active management.

Benchmark choice therefore matters enormously. Without an appropriate style benchmark, it is difficult to know whether outperformance or underperformance reflects the investment approach itself or the manager’s decisions within it.

What active management should add

The distinction between style and skill is useful when assessing active strategies in practice. The AIM Global Sustainable Value Cell (“AIM SV”), a fund advised by Accresco, combines the Quality and valuation disciplines discussed above with responsible-investment criteria, fundamental security selection, portfolio concentration and active position sizing. Since inception, the fund has generated approximately 9.5% per annum, compared with 8.7% for the VanEck Morningstar Global Wide Moat ETF, the investable QARP style comparator we use for this analysis.

That comparison is informative but not conclusive, because every benchmark has its own construction choices. A second perspective comes from peers: relative to 19 broadly comparable strategies, AIM SV has ranked in the top quartile across the year-to-date, one-year, three-year and five-year periods examined. Taken together, the two comparisons suggest that security selection, valuation judgement and portfolio construction have added value beyond the underlying style.

Putting the layers together

The return stack is useful, but it should not be mistaken for an equation. Market, factor, style and alpha exposures overlap, the underlying evidence comes from different periods and universes, and some apparent alpha will disappear once a portfolio is measured against a more appropriate benchmark. Its purpose is not to produce a precise decomposition of returns, but to clarify what is driving them.

That clarity matters both before and after capital is invested. Beta provides the starting point; factor and style benchmarks show what systematic exposures have contributed; and only the return that remains after those influences have been accounted for can reasonably be attributed to active judgement. Moving from beta to alpha is therefore less about adding complexity than becoming more precise about what is actually being owned and what is genuinely adding value.

What investors should focus on

The investment industry devotes enormous attention to forecasting what comes next. There will always be another interest-rate decision, election, technological breakthrough or shift in market leadership to interpret, each creating a new set of arguments about where capital should be deployed. Some of those forecasts will prove right. The difficulty is that even a correct view of the future does not necessarily translate into a successful investment if expectations are already reflected in prices.

A more durable approach is to understand the sources of return embedded in the portfolio. Broad equity ownership provides the foundation; systematic factors can alter the characteristics of that exposure; investment styles introduce further discipline; and active management must justify itself by adding value beyond all three. None will work equally well in every market environment, which is precisely why separating them matters. Without that distinction, investors risk confusing a favourable cycle with skill or abandoning a sound process because the market is temporarily rewarding something else.

After more than three decades in markets, my own framework has become simpler rather than more elaborate. I want to own productive assets, favour businesses with durable economics, remain disciplined about the price paid for them, and understand which part of the eventual return comes from the market, which from systematic exposures and which genuinely reflects active judgement. That does not remove uncertainty from investing, but it provides a more reliable basis for decision-making than trying to forecast every change in the market narrative.

At Accresco, we summarise that philosophy in three ideas: Better Businesses. Better Value. Better Results.

The first two are choices an investor can make. The third is what disciplined execution is intended to achieve over time.

Skip to content